Reimbursement percentage gets more attention than almost any other pet insurance feature. Yet the detail that actually changes your payout the most isn’t the percentage itself — it’s a calculation order most owners never think to ask about. Here’s both parts explained clearly.
The Basic Definition of Pet Insurance Reimbursement Rate
Your pet insurance reimbursement rate is the percentage of covered veterinary expenses your insurer pays back once your deductible has been met. Most US pet insurers offer a choice between 70%, 80%, and 90%. A smaller number offer 50%, and Figo and ASPCA offer up to 100% with certain deductible selections. The 80% tier is a common middle choice.
The Standard Formula
The most common calculation applies your deductible first, then the percentage:
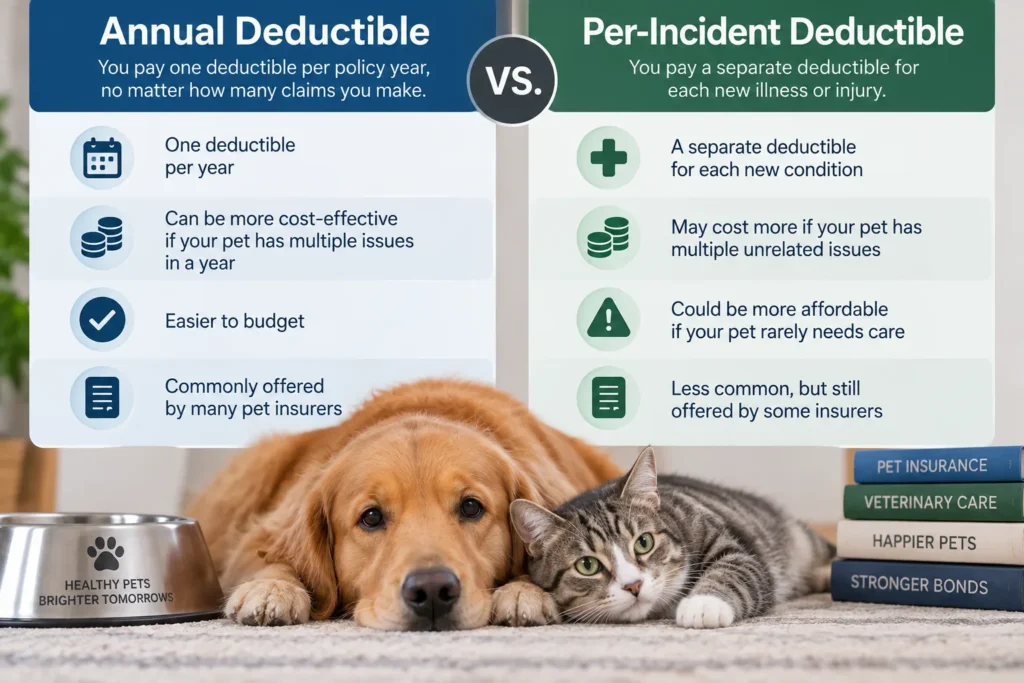
(Eligible vet bill − Deductible) × Reimbursement % = Amount paid by insurer
On a $2,000 bill with a $500 deductible at 80% reimbursement: ($2,000 − $500) × 80% = $1,200 reimbursed. You’re responsible for the remaining $800 out of pocket.
Why the Calculation Order Actually Matters More Than the Pet Insurance Reimbursement Rate Itself
This detail catches even attentive policyholders off guard, because it rarely appears front and center in marketing materials. Not every insurer applies the deductible and percentage in the same order, and the difference in your final payout is real, not trivial.
- Deductible applied first (most common): $1,200 bill, $200 deductible, 80% reimbursement → ($1,200 − $200) × 80% = $800 reimbursed.
- Percentage applied first, deductible subtracted after: Same bill and terms → ($1,200 × 80%) − $200 = $760 reimbursed.
The gap here looks modest, just $40, but it grows with the size of the claim. Ask any insurer you’re comparing which method they use, since “80% reimbursement” doesn’t mean the same dollar amount at every company. Pawlicy Advisor confirms that your reimbursement rate determines how much of the vet bill your insurer covers after your deductible is met, but doesn’t specify calculation order — which is exactly why you need to ask directly.
Real Math at Each Reimbursement Tier
Using a realistic $4,000 vet bill with a $250 deductible, here’s how the three common tiers compare:
- 90% reimbursement: insurer pays $3,375; you pay $625 ($250 deductible + $375 coinsurance).
- 80% reimbursement: insurer pays $3,000; you pay $1,000.
- 70% reimbursement: insurer pays $2,625; you pay $1,375.
Insurers technically call the remaining share you owe after the deductible — 10%, 20%, or 30% depending on your tier — your coinsurance. This term, borrowed from human health insurance, sometimes confuses pet owners coming from that system.
How Much More Does a Higher Reimbursement Rate Actually Cost?
Before you assume 90% is automatically the “better” choice, know this: bumping your reimbursement rate up increases your premium. That means the jump from 70% to 90% can add a meaningful amount to your monthly cost, not just a marginal one. Whether that trade-off is worth it depends on how much monthly premium increase you’re comfortable with in exchange for a smaller bill at claim time.
Which Reimbursement Rate Tier Should You Actually Choose?
- 90% reimbursement works best if you have limited emergency savings and want to minimize what you’d owe if a large claim happens. The higher premium buys you predictability at the moment you need it most.
- 80% reimbursement is the most commonly recommended “sweet spot.” It offers substantial coverage without the premium jump of the highest tier, while still keeping some cost-sharing on your end.
- 70% reimbursement works best if you already have a dedicated emergency fund. This calculated bet pays off specifically for owners whose pets stay relatively healthy, since the lower premium compounds in your favor over years without major claims.
A Real Cost Comparison: 70% vs. 80% on the Same Claim
For a $2,700 hip dysplasia surgery with an 80% reimbursement plan and a $500 deductible, you’d pay $940 out of pocket while insurance covers $1,760. At 70% on the same bill, you’d pay roughly $220 more. This difference compounds significantly over a pet’s lifetime, especially for pets with chronic conditions that need ongoing treatment rather than a single one-time claim.
Can You Change Your Reimbursement Rate Later?
Yes. Most insurers let you adjust your reimbursement percentage at renewal, which is genuinely useful as your pet ages. Bumping from 70% to 90% before a senior pet’s higher-risk years can be a reasonable strategy. Keep two things in mind, though: it raises your premium going forward, and any condition already diagnosed before the change still gets handled under the original policy terms. Switching tiers doesn’t retroactively improve reimbursement on an existing claim or condition.
Why “80% Reimbursement” Can Still Feel Lower Than Expected
Policyholders frequently discover that their effective reimbursement felt lower than the advertised percentage. This sometimes traces back to how a specific insurer calculates “eligible” costs versus the total bill, since not every line item on a vet invoice necessarily counts as reimbursable. Before enrolling, ask directly how a specific insurer defines “eligible expenses,” and read a couple of real customer reviews focused specifically on claims experience, not just pricing.
Bottom Line
Your pet insurance reimbursement rate determines what share of an eligible bill comes back to you after your deductible, with 80% as the most commonly chosen middle-ground tier. But the calculation order, deductible-first vs. percentage-first, can shift your actual payout even at the same advertised percentage. Confirm it directly with any insurer you’re comparing. A higher reimbursement rate genuinely costs more in premium, so the right tier depends less on chasing the highest number and more on how much monthly premium increase you’re comfortable trading for a smaller bill during an actual claim.
For how this interacts with your annual payout ceiling, see our pet insurance coverage limits guide.
Frequently Asked Questions
Is 90% reimbursement always worth the higher premium? Not necessarily. It depends on your emergency savings. If you already have $3,000-$5,000 set aside for vet costs, a lower reimbursement tier with a smaller premium can work out better over time, especially if your pet stays relatively healthy.
Does my reimbursement rate affect which conditions are covered? No. The reimbursement rate only affects how much of an eligible, covered bill you get back. It doesn’t expand or restrict which conditions or treatments are eligible for coverage in the first place.
Can I switch my reimbursement rate mid-policy year if my pet gets sick? Generally no. Insurers typically fix your reimbursement rate at quote time for the policy year, though most allow you to adjust it at renewal for the following year.
Sources referenced: Pawlicy Advisor (2025-2026 reporting).